Close Menu
Digital Trade Outlook

    Subscribe to DTO

    Get the latest intelligence on digital trade, cross-border payments and transaction banking, selected by our editors and delivered to your inbox.

    What's Hot

    Swift Will Make Stop and Recall Mandatory in November 2027. Will Fraud Victims Get Their Money Back Faster?

    November 19, 2026

    FinCEN Rewrites the Beneficial Owner Rules and Hands Banks More Judgement

    November 18, 2026

    Hong Kong Brings Swift Into Project Ensemble. Nothing Is Live Yet

    November 18, 2026
    LinkedIn X (Twitter)
    Digital Trade Outlook
    Subscribe
    • Home
      • Trade Finance & Transaction Banking
      • Cross-Border Payments
      • Supply Chain Finance
      • Digital Trade Infrastructure
      • Treasury & Liquidity
      • Risk & Compliance
      • Analysis
      • Executive Moves & Appointments
    • Executive Voice
    • Outlook Op-Ed
    • Insights
      • Analysis
      • Explainers
      • MLETR Adoption Tracker
    • Live Deals Tracker
    • Platform Directory
    • About Us
    • Advertise & Partner
    Digital Trade Outlook
    Home»Analysis»Swift Will Make Stop and Recall Mandatory in November 2027. Will Fraud Victims Get Their Money Back Faster?
    Analysis

    Swift Will Make Stop and Recall Mandatory in November 2027. Will Fraud Victims Get Their Money Back Faster?

    By Digital Trade OutlookNovember 19, 2026
    Swift logo

    From November 2027, every financial institution on Swift must send payment cancellation requests and responses through its Stop and Recall service, using ISO 20022 messages over FINplus. The MT n92 and n96 cancellation messages will be removed, free format MT n99 will be retired for cancellations, and the in-flow translation that lets MT and ISO 20022 users exchange recalls will end. Swift has already postponed this mandate once, so banks can keep exchanging cancellations bilaterally in either format until November 2027.

    Banks get access to the service with no setup: Swift will give it automatically to every eligible institution. The service routes each request to the right bank, chases it with automatic reminders and tracks it under one investigation reference. That still leaves each bank to find the original payment, check whether it has settled and answer the request. The mandate gives a bank the connection. Its own back office still has to do the work.

    That work matters most in fraud cases. In 2025 the FBI’s Recovery Asset Team worked with banks on 3,900 incidents involving $1.16 billion in attempted theft, and $679 million was frozen, a 58 percent success rate. International transfers made up a small share: 326 incidents, with $172 million frozen. The FBI tells victims to contact their bank immediately and request a recall. Two cautions apply to these figures. Frozen money has not yet been returned to anyone, and the figures measure a law enforcement process rather than Swift’s service.
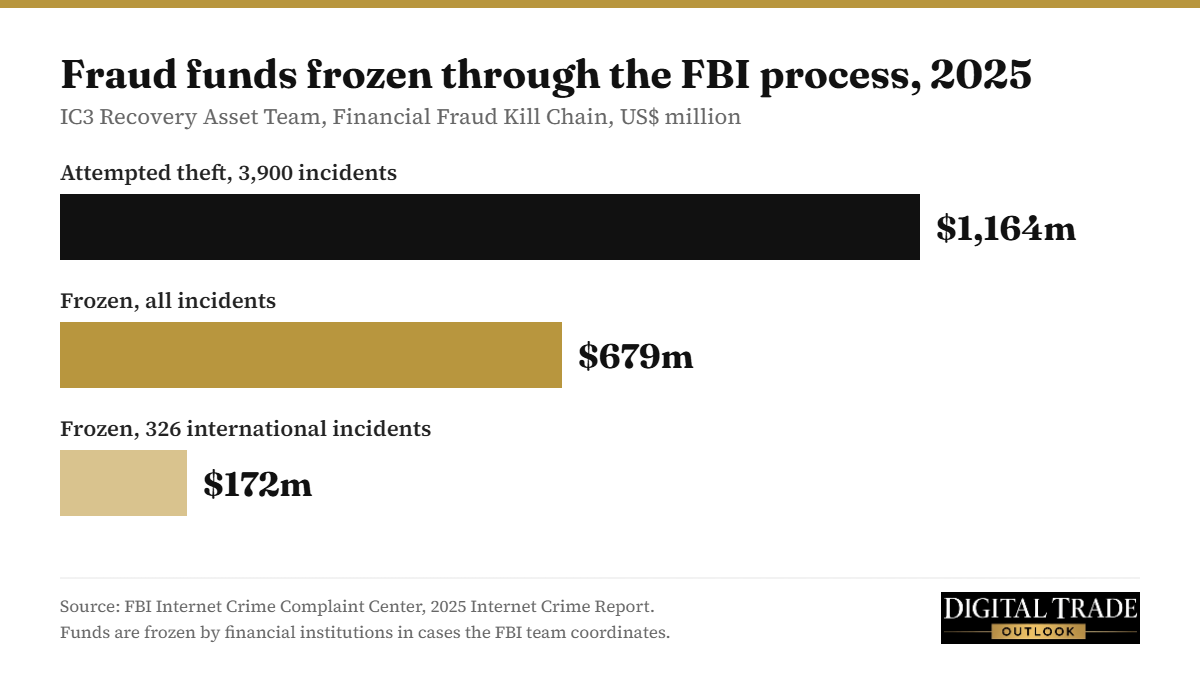
    Chart: In 2025 the FBI IC3 Recovery Asset Team worked on 3,900 incidents involving $1,164 million in attempted theft; $679 million was frozen, including $172 million in 326 international incidents

    The new format will help where it can. A camt.056 message must state why the payment is being cancelled, in a far more structured way than the old MT messages, and ISO 20022 has a standard code, FRAD, for payments of fraudulent origin. A receiving bank’s systems can recognise a fraud recall without anyone reading free text. They still cannot pull back money that has already been credited and moved on. A cross-border recall also has to travel back through every bank the payment passed, so it moves only as fast as the slowest bank in that chain.

    The date itself could move again. On 27 August Swift extended the structured address migration after several communities asked for more time. A 21 September update then pushed the deferred SR 2026 release, which includes exceptions and investigations messages, to 12 June 2027. For now Swift still lists November 2027 as the end of MT messages for cancellations and investigations, and banks should plan for that date.

    The number to watch is how fast banks answer recalls, not how many have switched formats. Swift publishes no figures on recall response times or on how much money is recovered, and until it does, nobody outside the banks can tell whether the migration helps victims. Treasurers do not need to wait for those figures. They can ask their banks now whether they use Stop and Recall, how quickly they send a recall after a fraud report and how they report progress on a case. The answers will show which banks are ready.

    Related on Digital Trade Outlook

    • When Standards Keep Changing, Will the Cost of Keeping Up Push Smaller Banks Out of Trade Finance?
    • Two Months Out, Can Banks Outside the Euro Area Convert and Credit an Instant Euro Payment in 10 Seconds?
    • FinCEN Rewrites the Beneficial Owner Rules and Hands Banks More Judgement

    Image: Swift logo

    Advertise & Partner
    Reach decision-makers in trade finance, transaction banking and cross-border payments with Digital Trade Outlook.
    Partner with us →
    camt.056 Cross-Border Payments Exceptions and Investigations Fraud Recovery ISO 20022 Payment Fraud Payment Recalls Stop and Recall SWIFT Transaction Banking

    Related Posts

    Hong Kong Brings Swift Into Project Ensemble. Nothing Is Live Yet

    DBS and J.P. Morgan Connect Their Deposit Tokens. The Weekend Gap Is Not Fully Closed

    ASEAN Signs Its Digital Economy Agreement and ADB Says Money Is Not the Constraint. Who Moves First?

    Executive Voice

    “Success isn’t measured by whether you’ve replaced a legacy system” – Avinash Ranjan, Lloyds Banking Group

    “Rather than any single technology or form of money replacing what exists today, we expect to see the emergence of a multi-rail environment” – Tsvetanka Nankova, Deutsche Bank

    “Corporates will forgive a delay they understand, but they will not forgive silence” – Sana Shah, Graystone Capital

    Our Analysis
    • Swift logo
      Swift Will Make Stop and Recall Mandatory in November 2027. Will Fraud Victims Get Their Money Back Faster?November 19, 2026
    • ASEAN and Asian Development Bank logos
      ASEAN Signs Its Digital Economy Agreement and ADB Says Money Is Not the Constraint. Who Moves First?November 15, 2026
    • Payments Canada logo
      Canada’s Instant Payment Rail Is Live and a Link With Europe Is Planned. What About the US?November 15, 2026

    Outlook Op-Ed

    Have an argument the industry should hear?

    Senior leaders in trade, payments and transaction banking can propose a piece.

    Propose an op-ed →
    Latest News

    FinCEN Rewrites the Beneficial Owner Rules and Hands Banks More Judgement

    November 18, 2026

    Hong Kong Brings Swift Into Project Ensemble. Nothing Is Live Yet

    November 18, 2026

    Two Days After Its Deposit Token Link, DBS Adds a USDC Channel

    November 18, 2026

    Subscribe to Updates

    Digital Trade Outlook
    Executive Voice

    “Success isn’t measured by whether you’ve replaced a legacy system” – Avinash Ranjan, Lloyds Banking Group

    November 18, 2026

    “Rather than any single technology or form of money replacing what exists today, we expect to see the emergence of a multi-rail environment” – Tsvetanka Nankova, Deutsche Bank

    November 17, 2026

    “Corporates will forgive a delay they understand, but they will not forgive silence” – Sana Shah, Graystone Capital

    October 27, 2026
    Analysis

    Swift Will Make Stop and Recall Mandatory in November 2027. Will Fraud Victims Get Their Money Back Faster?

    November 19, 2026

    ASEAN Signs Its Digital Economy Agreement and ADB Says Money Is Not the Constraint. Who Moves First?

    November 15, 2026

    Canada’s Instant Payment Rail Is Live and a Link With Europe Is Planned. What About the US?

    November 15, 2026

    Subscribe to Updates

    About Us

    Digital Trade Outlook is a global intelligence platform covering digital trade and cross-border commerce, delivering independent insights across transaction banking, trade finance, payments and modern trade infrastructure.

    Reach Us

    Editorial, partnerships and research:
    editorial@digitaltradeoutlook.com

    Advertise & Partner →

    Company
    • About Us
    • Executive Voice
    • Advertise & Partner
    • Privacy Policy
    • Editorial Standards
    • Terms of Use
    © 2026 Digital Trade Outlook.

    Type above and press Enter to search. Press Esc to cancel.