
Bilateral trade in the UAE-India corridor has now cleared US$100 billion for two years running, and UAE-India trade finance looks very different from a few years ago. The CEPA duty cuts drew in a wave of mid-sized Indian manufacturers and exporters that had never shipped through the Gulf before. They trade in smaller amounts, more often, and many arrive without a credit history at Gulf banks.
For Sana Shah of Graystone Capital, that change puts the weight on how a deal is presented to lenders. Graystone starts with the trade cycle rather than the balance sheet, checks every flow against invoices, shipping and customs records, and then matches each transaction to the bank, non-bank lender or private credit fund best placed to price its risk.
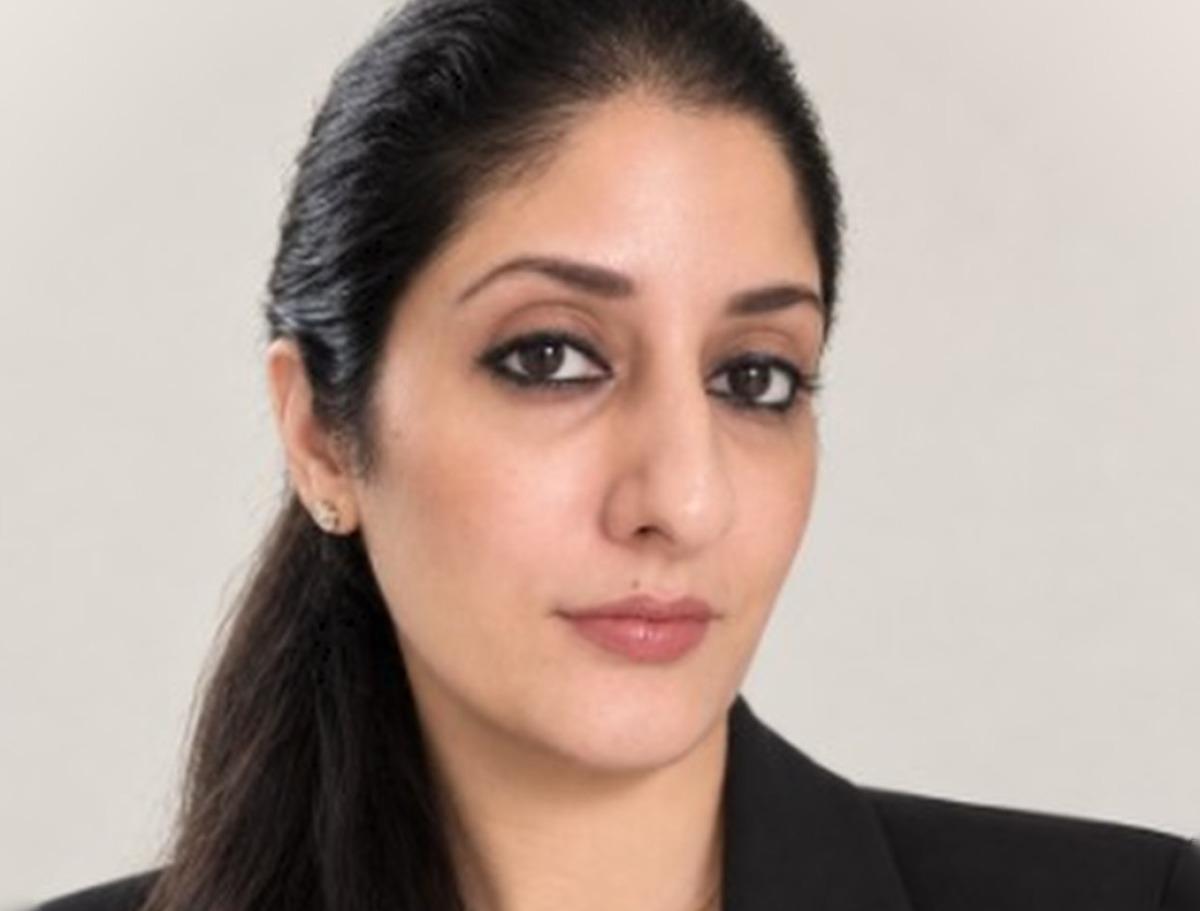
Sana Shah, Assistant Vice President, Trade Finance and Credit Management, Graystone Capital, spoke with Digital Trade Outlook about how the UAE-India CEPA has reshaped trade finance demand in the corridor, the shifting balance between letters of credit and open account terms, how Graystone turns a client’s trade flows into a lender-ready proposal, how it chooses between banks, non-bank lenders and private credit, what still keeps trade documents on paper across the GCC and India, and what will set payment providers apart as cross-border payments get faster.
How CEPA changed UAE-India trade finance
Digital Trade Outlook: How has trade finance demand changed since the UAE-India CEPA came into force, and which sectors are driving it?
Sana Shah, Assistant Vice President, Trade Finance and Credit Management, Graystone Capital: CEPA has done more than add volume to the corridor. It has changed who is trading along it. Bilateral trade has now been above US$100 billion for two years running: about US$100 billion in FY2024-25 and US$101.25 billion in FY2025-26. Non-oil trade is now close to two-thirds of the total, and both governments are aiming for US$200 billion by 2032.
For trade finance, the bigger change is who is asking for it. CEPA’s duty cuts brought in many mid-sized Indian manufacturers and exporters that had never traded through the Gulf before. They tend to ship smaller amounts more often, and many have no long credit record with Gulf banks. So demand has moved towards working capital that matches each trade cycle: pre-shipment finance, receivables finance and inventory funding. Large one-off facilities matter less.
The main sectors are:
- Gems and jewellery. Exports to the UAE grew 10.5% in FY26 to about US$8.7 billion.
- Electronics and smartphones.
- Engineering goods.
- Food and agricultural products, helped by the UAE’s food-security buying.
- Re-exports through UAE hubs to Africa and Central Asia.
The wider GCC is following the UAE. The India-Oman CEPA came into force on 1 June 2026, and India-GCC free trade talks formally began in February 2026.
The West Asia conflict this year has also changed what clients need. Freight costs spiked and shipments were rerouted around the Strait of Hormuz. That lengthened cash cycles, so clients needed bridge funding and protection against risk more than cheap credit. India’s export credit insurer, ECGC, temporarily raised its cover on Gulf shipments to 95%, which shows how sharply perceived risk rose.
How is the balance between letters of credit and open account terms shifting, and what does it mean for how buyers and sellers share risk?
Over the long term, trade is moving towards open account terms. Established relationships have mostly made that move already, for example Indian exporters selling to the same UAE distributors repeatedly, or companies trading with their own group entities. Letters of credit remain the norm in four situations:
- with new counterparties
- in commodities and high-value goods such as bullion and precious stones
- in project-related supply into Saudi Arabia
- in any trade where the buyer’s country risk is uncertain
The disruption in 2026 slowed the move away from letters of credit for a while. Many exporters asked for confirmed letters of credit again, at least for new or larger shipments.
Under open account terms, the seller carries the buyer’s credit risk and waits to be paid. That is why demand has grown for receivables finance, factoring and credit insurance. These products let the seller pass that risk on, or turn the unpaid invoice into cash, without asking the buyer for a letter of credit. The ICC Trade Register shows receivables finance gaining share globally, and this corridor matches that trend. In practice, risk now sits less between buyer and seller and more with financiers and insurers who price it. Sellers that can document their receivables properly can usually get open account deals financed on good terms.
How does Graystone Capital assess a business’s trade flows and turn its funding needs into a proposal that meets lenders’ credit requirements?
We look at the trade cycle first and the balance sheet second. A trading business’s financial statements often understate how strong it is, because its real collateral is the goods and receivables moving through it. We map each step of the cycle:
- who the client buys from and sells to
- payment terms on both sides
- shipping routes and documents
- the cash conversion cycle
- how concentrated the business is in a few buyers, suppliers or products
We then check those flows against invoices, shipping documents, customs and GST records, and bank statements. This lets us show lenders actual trade, not a forecast.
Next we size the facility to the trade cycle, not to a round number. We also choose a structure that repays itself as trades complete, for example:
- borrowing bases (a credit limit tied to the value of eligible receivables or stock)
- assigned receivables
- collection accounts that lenders control
- credit insurance where it is needed
The proposal we take to lenders follows their own credit criteria: KYC (know-your-customer checks) and ultimate beneficial ownership, sanctions and dual-use screening (which matters even more given the region this year), counterparty quality and security. We also state the risks openly and show how each one is mitigated. In our experience, a well-documented and honest credit file is the fastest route to approval.
Banks, non-bank lenders and private credit funds all compete for trade finance. How does Graystone decide which source of capital fits a transaction?
We start with the transaction, not the lender. The factors are:
- tenor
- deal size
- the obligor’s credit profile
- how much security is available
- how fast the client needs funding
- the client’s tolerance on price
Banks are still the cheapest and most suitable option for well-rated borrowers, collateralised deals, and anything that needs a letter of credit issued or confirmed.
Non-bank and fintech lenders are usually better for smaller, high-frequency receivables finance where speed and digital onboarding matter.
Private credit fits larger or more complex deals that banks find hard to hold: pre-export and inventory finance, sub-investment-grade obligors, longer tenors, or deals where the bank has hit its country or sector limit. That gap is likely to grow as the Basel 3.1 capital rules push banks to distribute more trade assets rather than keep them. GCC private credit is still small, around US$6 billion according to Moody’s, but it is growing quickly. Gulf sovereign and institutional capital is increasingly looking at shorter-dated, self-liquidating assets like trade finance.
More and more of our deals use several sources together. For example, a bank issues or confirms the letter of credit while a fund finances the receivables or the inventory. Our job is to arrange the capital so each party holds the risk it is best placed to price.
What is still holding back the move from paper to digital trade documents in the GCC and India?
There are four main obstacles.
Legal certainty. A digital trade document is only useful if it is legally valid at every point in the chain. Abu Dhabi Global Market (ADGM) aligned its rules with the UNCITRAL Model Law on Electronic Transferable Records (MLETR) in 2021, and India replaced its 1856 bills of lading law in 2025. But recognition is still uneven across jurisdictions. If one party, port or court in a transaction may not accept an electronic original, everyone falls back to paper.
Interoperability. The platforms do not reliably work with each other. In the latest industry survey (FIT Alliance, October 2026), about half of companies said they use electronic bills of lading in some form, but only about 11% use them exclusively, and only around 22% of banks report even partial use. If your counterparty’s bank is on a different platform, you print.
SME capability and cost. Many smaller exporters, freight forwarders and customs brokers are still paper-based. Switching costs fall unfairly on the smallest firms in the chain.
Lender practice. Credit and operations teams, insurers and auditors are still used to checking physical documents. This is the main issue from where I sit, because digital documents are actually safer for lenders. A properly controlled electronic record makes duplicate financing, where the same goods or invoice are financed twice, much harder. That is a fraud risk the industry knows well. As lenders start to give better pricing or faster approvals for digital, verifiable documents, I expect adoption to speed up.
As SWIFT gpi and similar initiatives make payments faster, what will set banks and payment providers apart in serving corporate clients?
Speed is becoming the minimum clients expect. Swift says about 90% of cross-border payments on its network reach the beneficiary’s bank within an hour. The ISO 20022 messaging standard became mandatory for cross-border payments in November 2025, which means much richer payment data now travels with each payment. The gap is the last leg. Only around 43% of payments reach the end customer’s account within an hour, against a G20 target of 75% by 2027.
Providers will compete on three things:
- Transparency. Fees, FX rates and expected arrival time should be shown before the payment is sent. Each payment should be tracked end to end, and that tracking should feed directly into the client’s treasury and ERP systems instead of sitting in a bank portal.
- Reliability. Payments should go through without manual fixes. That means using the richer ISO 20022 data to cut rejections, and handling sanctions screening and compliance holds quickly and predictably. Holds are where most corporate payments get stuck today, especially in trade involving the Gulf.
- Issue resolution. Clients need a named contact who can see the whole payment chain, investigate and recall payments quickly, and explain clearly why a payment is stuck. Corporates will forgive a delay they understand, but they will not forgive silence.
Local-currency rails will also matter in this corridor. Examples are rupee-dirham settlement and the planned links between India’s and the UAE’s payment and messaging systems. Providers that combine these rails with Swift, and help clients choose the right route for each payment, will stand out.
The conversation continues
Join the discussion on LinkedIn
Digital Trade Outlook shared this interview with Sana Shah on LinkedIn. Read what peers are saying and add your view.
Join the discussion on LinkedIn ↗Join the discussion on X ↗