
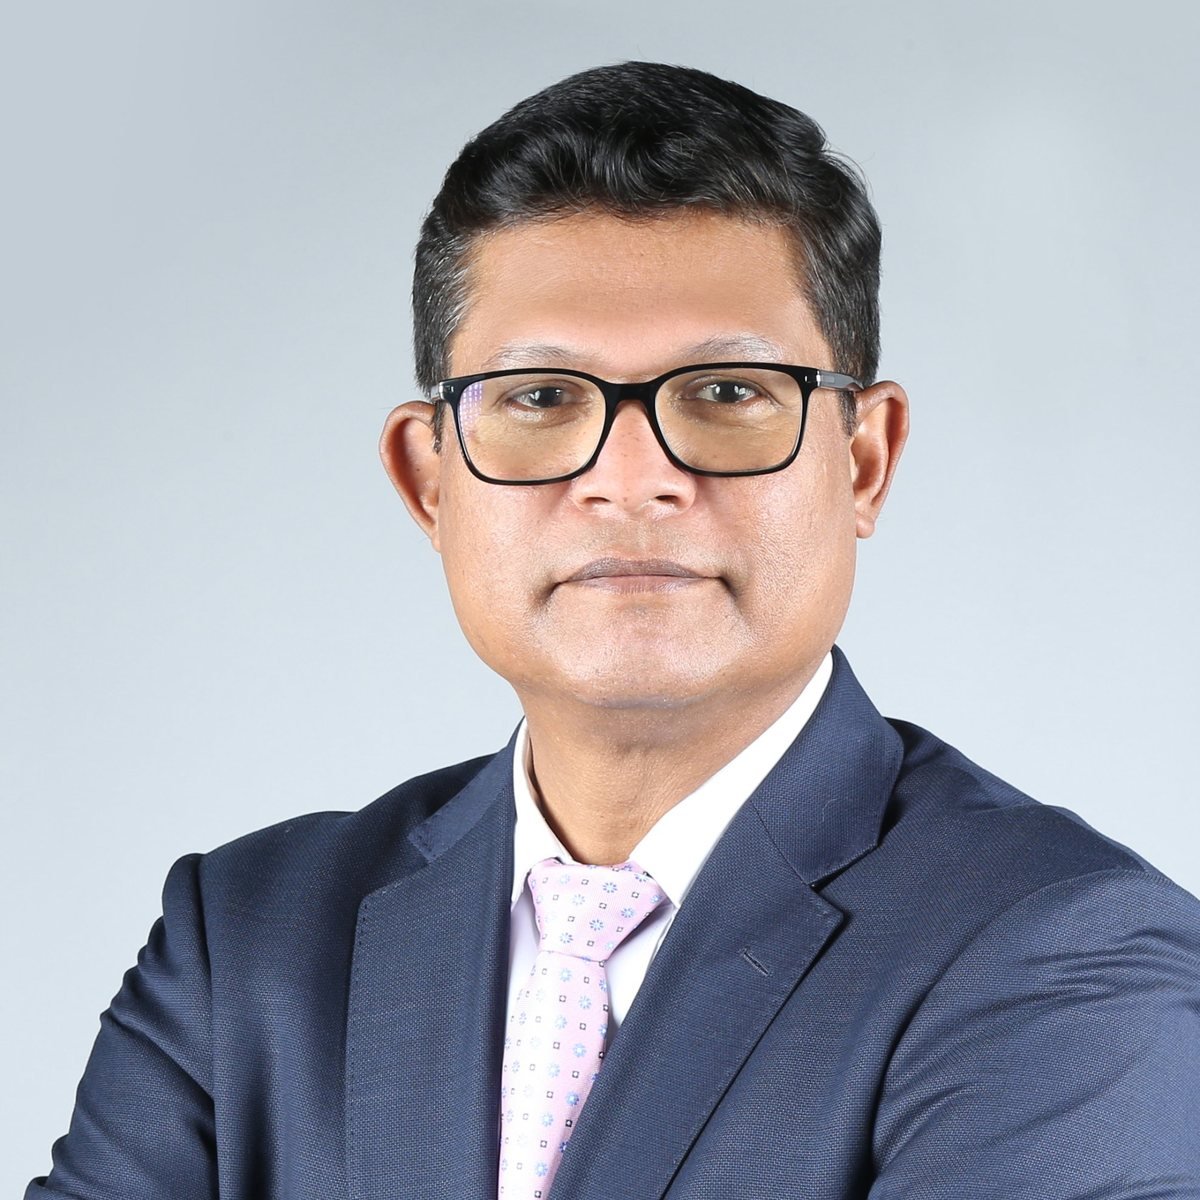
Development banks are usually judged on how much capital they deploy. For Emirates Development Bank, the harder test is how quickly that capital reaches the businesses that need it. EDB has a mandate to deploy AED 30 billion in financing support to UAE-based companies by 2026, and Zaman Jayman sees transaction banking as the engine that connects the bank to them.
Ask him what holds SMEs back and he does not point to a shortage of money. He points to access: lengthy documentation, collateral requirements, and financing that arrives out of step with a business’s cash-flow cycle.
Zaman Jayman, Senior Vice President, Transaction Banking, Emirates Development Bank, spoke with Digital Trade Outlook about how EDB’s AED 30 billion development mandate shapes its transaction banking and working-capital proposition, the barriers that keep SMEs from timely trade finance, why cross-border payments remain harder than they should be, what separates trade digitalisation that gets adopted from initiatives that stall, and which transaction banking capabilities corporates now treat as basic.
Inside Emirates Development Bank’s SME finance strategy
Digital Trade Outlook: Emirates Development Bank has a mandate to deploy AED 30 billion in financing support to UAE-based companies by 2026. How does this development mandate shape the transaction banking and working-capital solutions EDB provides to businesses?
Zaman Jayman, Senior Vice President, Transaction Banking, Emirates Development Bank: EDB’s strategic vision is embedded in supporting five major priority sectors: Manufacturing, Healthcare, Renewables, Food Security and Advanced Technology. EDB’s development mandate fundamentally shapes Transaction Banking and Working Capital as growth-enabling solutions, not simply banking products. To deliver AED 30 billion of financing to 13,500 companies, EDB must help businesses access funding, manage cash flows, trade efficiently and scale with confidence.
This means EDB’s Transaction Banking and Working Capital proposition is built to:
- Enable growth: Provide working-capital facilities, trade finance and cash management solutions that address the funding needs of businesses as they scale.
- Improve access to finance: Use transactional data, digital channels and simplified processes to make financing more accessible, faster and more responsive, particularly for SMEs and priority sectors.
- Support the full business cycle: Connect collections, payments, liquidity, trade and working-capital financing into an integrated proposition rather than offering standalone products.
- Drive digital adoption: Deliver seamless, digital-first journeys that reduce documentation, turnaround times and operational friction for businesses.
- Deepen customer relationships: Make Transaction Banking the entry point and engagement engine for EDB, generating CASA, transactional flows and actionable customer data while creating opportunities for broader financing.
- Align capital with the UAE’s economic priorities: Target solutions toward priority sectors and businesses that contribute to diversification, industrialisation, innovation and the UAE’s broader economic development agenda.
Digital Trade Outlook: From your perspective, what are the main barriers preventing businesses, particularly SMEs, from accessing timely trade finance and working capital, and how should the banking industry address them?
The biggest barrier is often not the availability of capital, but the ability to access it quickly, confidently and in a form that matches the SME’s cash-flow cycle. SMEs frequently face limited financial information, lengthy documentation, complex approval processes, collateral requirements and a mismatch between when working capital is needed and when financing becomes available.
The banking industry should respond by moving from a collateral- and documentation-led model to a more data-driven, cash-flow-led and digitally enabled approach.
Key priorities should be:
- Simplify access: Reduce documentation and streamline onboarding, approvals and utilisation.
- Use data better: Leverage transaction flows, account behaviour, trade activity and digital records to strengthen credit assessment.
- Finance the cash-flow cycle: Align facilities with actual receivables, payables, inventory and trade cycles rather than relying primarily on static balance-sheet metrics.
- Digitalise trade finance: Create end-to-end digital journeys that reduce turnaround time and operational friction.
- Provide proactive financing: Use transactional insights to identify funding needs before they become constraints.
- Build integrated propositions: Combine cash management services such as payments, collections, liquidity, trade finance and working capital into one ecosystem.
Digital Trade Outlook: UAE businesses operate across multiple trade corridors and currencies. What continues to make cross-border payments more difficult than they should be, and where are you seeing meaningful progress?
Cross-border payments remain more complex than they should be because the underlying infrastructure is fragmented. Different countries operate with different payment rails, formats, regulatory requirements, sanctions controls, currencies and beneficiary information standards. For businesses, this translates into multiple data requirements, manual interventions, higher costs and uncertainty around processing times.
The key challenge is therefore not simply moving money across borders: it is making the journey predictable, transparent and seamless for the customer.
Digital Trade Outlook: Paper-based documentation and manual processes remain common in trade finance. Where has digitalisation delivered tangible results, and what separates initiatives that achieve adoption from those that stall?
Digitalisation has delivered the greatest impact where it removes friction from the customer journey, not simply where it replaces paper with a digital form. Tangible results are being seen in digital trade applications, electronic document submission, automated workflow and approvals, real-time status tracking, and integration between trade, payments and core banking platforms. These reduce processing time, manual errors and operational effort while improving transparency for customers.
However, technology alone does not guarantee adoption. Initiatives succeed when they are built around the customer and supported by strong operational readiness.
Digital Trade Outlook: Corporate expectations of their banks have changed considerably. Which transaction banking capabilities do businesses now regard as basic requirements, and where is the industry still struggling to keep pace?
Corporate expectations have shifted from “banking services” to “always-on business infrastructure.” Businesses now expect transaction banking to be digital, integrated, fast, transparent and reliable, with the bank enabling their operations rather than creating additional administrative work. The industry still continues to struggle with the operational requirements. However, with digitalisation, that would be addressed to a large extent.
Read more conversations with transaction banking leaders in our Executive Voice series.
The conversation continues
Join the discussion on LinkedIn
Digital Trade Outlook shared this interview with Zaman Jayman on LinkedIn. Read what peers are saying and add your view.
On LinkedIn, as of 13 October 2026