
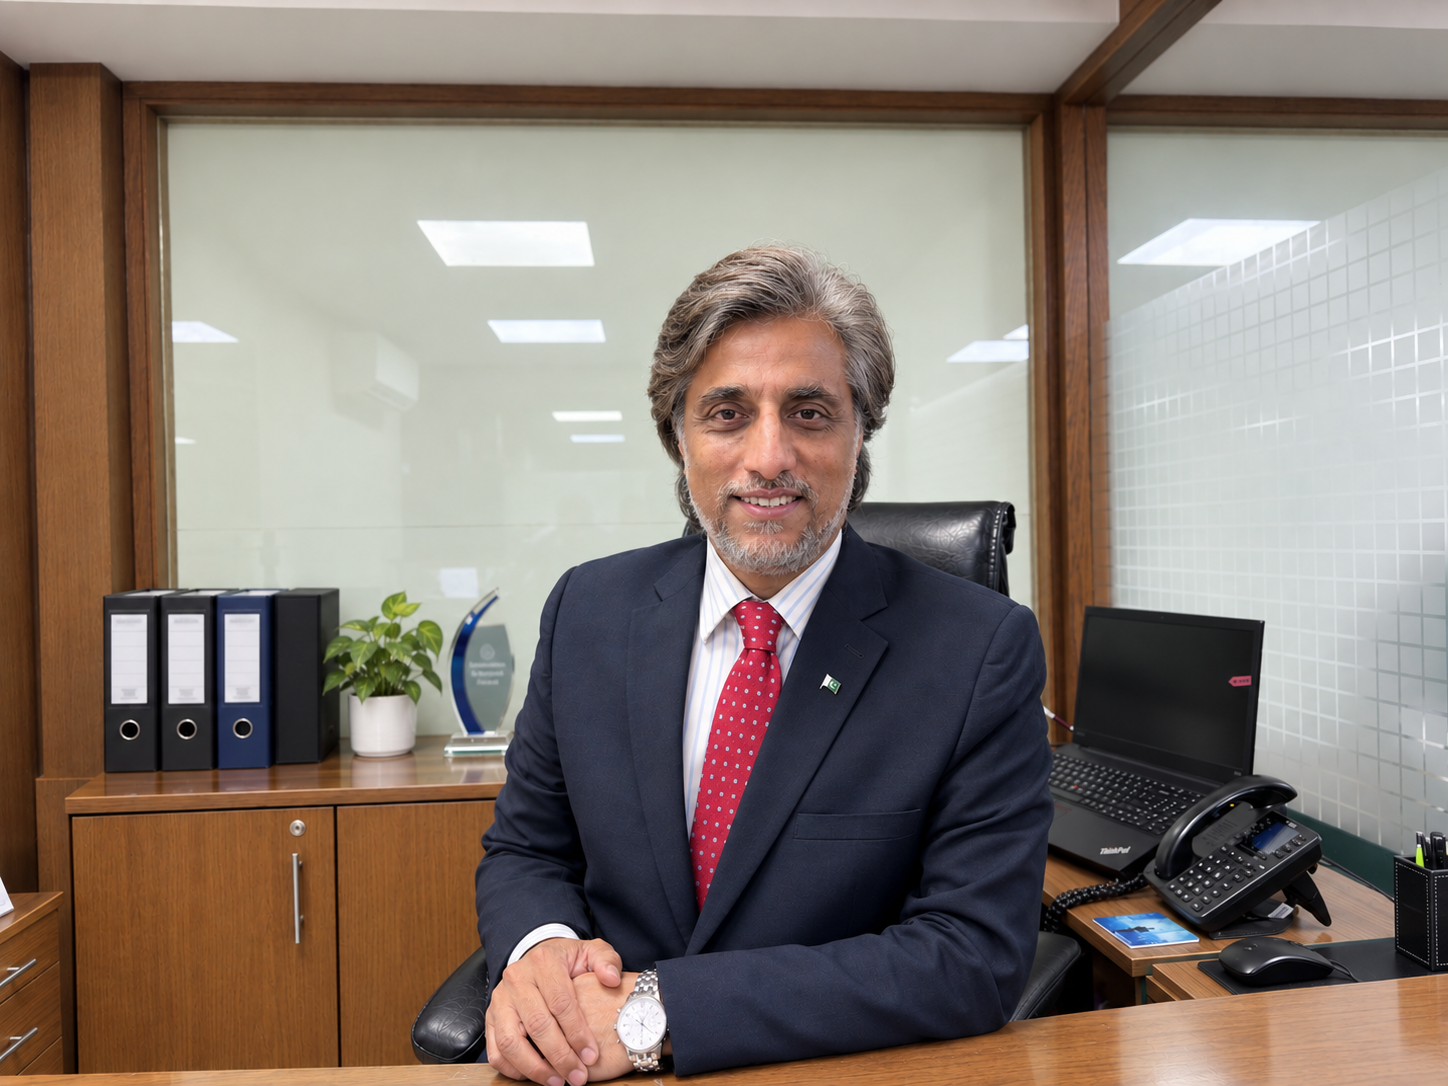
Most conversations about transaction banking start with large corporates: their ERP integrations, their host-to-host links, their treasury teams. Much of Muhammad Jawad Shami’s work at HABIBMETRO sits below that line. It is about SMEs and mid-market firms that run on cash, cheques and thin IT budgets, and that still need clear visibility over their money without the cost of heavy integration.
Ask him what will carry the bank through its next phase and he does not point to a single product. He points to architecture: an integrated technology core that can absorb growth in users and branches while keeping paperwork and compliance moving quickly and safely.
Muhammad Jawad Shami, Executive Vice President, Head Transaction Banking, HABIBMETRO, spoke with Digital Trade Outlook about how the Bank’s core value of Trust anchors its operations, driving the institution to forge stronger stakeholder partnerships through Integrity, Responsibility, Respect, Commitment, and Teamwork. He explained how this value-driven framework shapes how the Bank serves SMEs differently from large corporates, accelerates digitization within Pakistan’s transaction banking and trade finance sector, and strengthens the internal capabilities needed to sustain its market momentum.
Digital Trade Outlook–How is HABIBMETRO’s transaction banking strategy evolving to support the changing priorities of corporate and commercial clients in Pakistan?
Muhammad Jawad Shami, Executive Vice President, Head Transaction Banking, HABIBMETRO: HABIBMETRO is rapidly shifting its transaction banking strategy to focus on digital integration, end-to-end operational efficiency, and personalized corporate ecosystems to support the changing requirements of its corporate and commercial clients. Traditionally anchored by its market-leading strength in trade finance, the bank has modernized its transaction frameworks to cater to real-time transparency, automated working capital cycles, and remote governance.
The bank is focusing on five main areas to meet changing client needs:
- All-in-One Digital Platforms: Moving clients to online portals like Net2Bank so businesses can handle bulk payments, payroll, and collections directly from their dealers or from their own offices.
- Instant Data Sharing: Using modern tools (like SFTP/APIs and automated emails) to give corporate clients real-time updates on their account balances and cash flows.
- Faster Trade Finance: Digitizing import and export paperwork to help businesses move goods and secure funding across borders much faster.
- Capital Market & Regulatory Synchronization: As the State Bank of Pakistan drives the formalization and digitization of capital flows, HABIBMETRO aligns its strategy with broader capital market networks.
- Specialized Subscription Desks: To smooth corporate capital adjustments, the bank utilizes dedicated shares subscription platforms. This handles book building, initial public offerings (IPOs), bonus shares handling, and tax-adjusted digital dividend payments through a single point of contact.
As IFC and other development finance institutions scale up SME lending partnerships across Pakistan’s banking sector, how are cash management and liquidity tools evolving to serve SME and mid-market clients differently from larger corporates?
As the International Finance Corporation (IFC) and other development finance institutions (DFIs) aggressively scale up risk-sharing facilities and local currency lending partnerships across Pakistan’s banking sector, cash management and liquidity tools are undergoing a major structural shift. To bridge Pakistan’s significant SME financing gap, HABIBMETRO Bank is moving from traditional, rigid corporate banking frameworks by rolling out digital platforms for cash management and digital supply chain finance platforms tailored strictly to the operational realities of Small and Medium Enterprises (SMEs) and mid-market clients.
1. Seamless, Digital Portals vs. Heavy ERP Integrations
While large multinationals require deeply integrated, custom-coded Host-to-Host (H2H) or SFTP connections to sync their heavy ERPs (like SAP or Oracle), mid-market and SME clients cannot support that IT overhead.
- HABIBMETRO launched simplified, web-based corporate portals, “Net2Bank”.
- The “Net2Bank” platform provides immediate, real-time transaction visibility, bulk salary disbursements, and digital tax/customs payments (via PSID) through plug-and-play interfaces that require zero technical deployment from the business owner.
2. Automated Collections and “Branchless” Cash Drop-Offs
Large corporates dictate electronic payment terms to their buyers. SMEs in Pakistan, however, deal with retail value chains heavily reliant on cash or physical cheques.
- HABIBMETRO built a hybrid digital-physical collection suite offering various solutions. For instance, it uses CIT (Cash Collections services from customer premises) and collaborates with different fintechs to route SME loan repayments and cash collections through their platforms.
3. Rapid Transition to Standardized Islamic Liquidity Tools
A massive differentiator for the Pakistani market is the high demand for Shariah-compliant tools from the SME sector. According to IFC data, a significant percentage of SMEs historically stayed “new-to-bank” or under-banked due to religious reservations regarding conventional credit and interest-bearing accounts.
- Under the guidance of the State Bank of Pakistan’s (SBP) structural transformation policies, cash management tools for SMEs are aggressively shifting toward Islamic banking products like Mudarabah and Ijarah frameworks.
- These offer profit-sharing on floating business deposit funds and non-interest-based supply chain factoring, giving mid-market clients access to formal treasury yields that were previously not available for this segment.
HABIBMETRO is also offering a product program-based digital portal for cash and micro-lending capabilities under its digital supply chain program to meet the working capital requirements of SMEs and medium enterprises.
Trade finance remains central to Pakistan’s domestic and international commerce. How is digitalisation helping improve the speed, transparency, and overall experience of trade transactions?
Digitalization is transforming trade finance in Pakistan by replacing slow, manual paperwork with fast, automated online portals. Backed by the State Bank of Pakistan (SBP) and the Federal Board of Revenue (FBR), these changes help businesses move goods faster, track their funds with complete clarity, and improve the trading experience in three simple ways:
- Faster Processing: Platforms like the Pakistan Single Window (PSW) allow traders to submit import and export data online just once. This shares information instantly with customs and banks, cutting cargo approval times from days to hours.
- Real-Time Transparency: Trade portals allow businesses and regulators to track the exact status of their shipments and bank payments. This provides clear, live updates and eliminates hidden delays.
- Easier Access for Everyone: Customers no longer need to visit bank branches or pay for physical document couriers. Online portals make it easy and affordable for SMEs and smaller businesses to open Letters of Credit (LCs) at their convenience.
How can transaction banking solutions help SMEs and larger corporates manage working capital more effectively and build more resilient supply chains?
Transaction banking solutions help both SMEs and large corporations manage their day-to-day money (working capital) and build stronger supply chains in three simple ways:
- Faster Access to Cash: Instead of waiting 60 or 90 days to get paid by a buyer, suppliers can get their invoices paid almost immediately by the bank. This gives small suppliers quick cash to keep manufacturing, while allowing large corporate buyers to hold onto their funds longer and reduce working capital requirements.
- Real-Time Cash Tracking: Automated online portals show exactly when money is coming in and going out. This eliminates unexpected cash shortages and helps businesses accurately plan for upcoming expenses, like buying raw materials or paying bills.
- Stronger Supplier Networks: If a single supplier runs out of cash, the entire supply chain stops. By providing suppliers with quick, easy access to short-term funding and digital payments, banks ensure that production lines never halt due to money issues.
Trade finance, including letters of credit, import financing, and export bills collection, remains central to Pakistan’s banking sector. Where specifically are automation and data analytics changing how these traditionally paper-heavy instruments are processed and monitored?
Automation and data analytics are changing the most slow-moving, paper-heavy parts of trade finance in Pakistan. At HABIBMETRO, we are collaborating with the State Bank of Pakistan (SBP) and fintech platforms to transform three specific areas:
- Digital Document Scanning: Instead of bank workers manually checking piles of trade papers for errors, banks now use AI-powered software to instantly read invoices and shipping documents. This automatically checks for mistakes and speeds up the creation of Letters of Credit (LCs).
- Automatic Fraud Tracking: To prevent illegal price manipulation, the State Bank of Pakistan and the Pakistan Single Window (PSW) now use data analytics portals. These systems automatically cross-check the declared price of goods against live global market rates to stop fraud instantly.
- Live Shipment & Payment Tracking: Instead of waiting for physical documents to be couriered across borders, banks are digitally linked directly to customs and ports. This allows businesses and banks to track the exact status of import and export bills in real time.
With HABIBMETRO’s credit rating recently upgraded to AAA and its digital platform expanding alongside branch growth, what internal capability, whether technology, talent, or process, do you see as most critical to sustaining that momentum over the next three years?
I personally believe that sustaining the newly upgraded AAA rating and parallel expansion requires an agile core, making integrated technology architecture the single most critical internal capability over the next three years.
Here is why it matters most, along with the other key factors:
- Modern Technology: The bank needs a powerful digital system that can handle millions of new users without slowing down, keeping both online banking and branches perfectly connected.
- Smart Talent: Employees must be trained enough to help customers use new digital tools alongside traditional banking services.
- Fast Processes: The bank needs to automate its paperwork so opening accounts and checking compliance happens quickly and safely.
In short, smart technology acts as the engine, while trained staff and fast workflows keep the bank moving forward safely.
The conversation continues
Join the discussion on LinkedIn
Muhammad Jawad Shami shared this interview on LinkedIn. Read what peers are saying and add your view.
Across 2 LinkedIn posts, as of 13 October 2026
- Also on the Digital Trade Outlook page3 reactions