
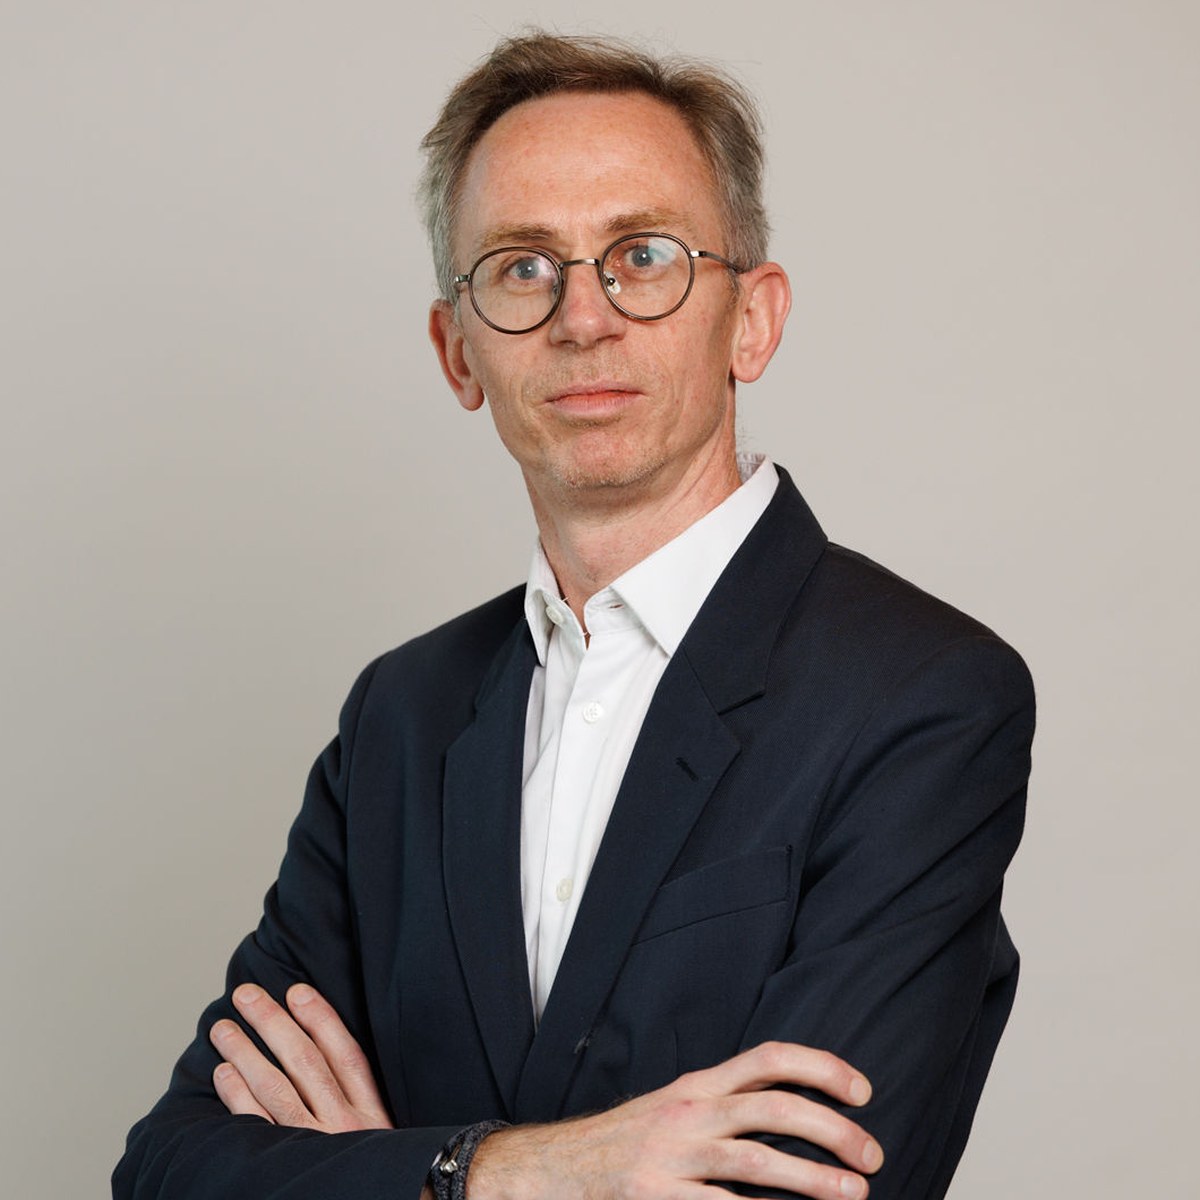
Most banks describe trade transformation as a technology story. For Arnaud Declochez, CIO Trade Finance, BNP Paribas CIB, the harder work sits elsewhere: in how people, processes and systems operate together, and in the discipline to let the operating model choose the technology rather than the other way round.
Ask him what will matter most over the next three years and he looks past AI. His answer is simplification: fewer layers of legacy complexity, cleaner architecture, and platforms that are easier to evolve.
Arnaud Declochez, CIO Trade Finance, BNP Paribas CIB, spoke with Digital Trade Outlook about the lessons from BNP Paribas’s trade transformation and digitalisation, how the bank prioritises trade finance technology investments, where AI is delivering practical value in document checking, what still stops trade data moving without manual re-entry, how a global platform balances standardisation with local requirements, and why simplification will be the defining technology priority for trade finance.
How BNP Paribas approaches trade finance technology
Digital Trade Outlook: As BNP Paribas pursues trade transformation and digitalisation, what has required the most effort to change in established systems, and what lessons would you share with banks undertaking similar work?
Arnaud Declochez, CIO Trade Finance, BNP Paribas CIB: The most challenging aspect of trade transformation has not been replacing technology. It has been changing the way people, processes and systems operate together.
One key lesson is that technology should not drive the operating model; the target operating model should drive the technology choices. Successful transformation requires a clear vision of the future roles, responsibilities and customer experience, combined with strong change management and continuous engagement with operational teams. Digital transformation should be approached as an end-to-end business transformation rather than a technology project. Process and people are key. Simplifying processes, standardising data and aligning governance are often more important than introducing new tools. Otherwise, the risk is simply to automate inefficient processes and execute them faster.
Secondly, trade finance platforms are deeply embedded in banks’ operations and often support multiple products, jurisdictions and regulatory frameworks. Modernising them while maintaining service continuity requires careful balance.
Finally, we believe it is key to focus on incremental value. Large-scale transformations are more successful when they deliver tangible business benefits through a series of manageable steps rather than a single big-bang approach.
Digital Trade Outlook: How is BNP Paribas prioritising its trade finance technology investments? Could you share one example of an improvement that has made a measurable difference to clients?
We prioritise investments that simultaneously improve client experience, operational efficiency and scalability. Rather than focusing on technology for its own sake, we look for initiatives that reduce friction in the client journey, automate routine activities and strengthen resilience across the trade ecosystem.
One area where we have seen clear benefits is the digitalisation of client interactions and request management. By moving away from email-driven processes towards more structured and digital workflows, clients benefit from greater transparency, faster processing and more predictable turnaround times. At the same time, operations teams are able to focus more on value-added activities rather than administrative tasks.
Digital Trade Outlook: In trade document checking and exception handling, where is AI delivering practical value, and where does human judgement remain essential?
AI is proving particularly effective in areas such as document classification, data extraction, information retrieval, consistency checks and compliance automation. These activities are often time-consuming, repetitive and involve large volumes of information, making them ideal candidates for augmentation through AI.
However, trade finance remains a business built on risk assessment, legal interpretation and client relationships. Human expertise is still essential when evaluating discrepancies, assessing unusual transactions, considering legal implications or making risk-based decisions.
The future is not about replacing experts. It is about providing them with better tools so they can spend less time searching for information and more time applying judgement where it matters most.
Digital Trade Outlook: With more jurisdictions adopting laws aligned with MLETR, what remains the biggest obstacle to banks, corporates and trade platforms exchanging data without manual re-entry, and what would help overcome it?
Progress on legal recognition of electronic trade documents is an important milestone, but legal frameworks alone will not eliminate manual processing.
The bigger challenge is interoperability. Different participants in the trade ecosystem often operate on different platforms, use different data models and follow different implementation standards.
To unlock the full benefits of digital trade, the industry needs greater convergence around data standards, stronger API connectivity and increased collaboration between banks, corporates, fintechs and platform providers. The long-term objective should be seamless exchange of trusted data rather than simply digitising existing documents.
Digital Trade Outlook: How do you balance a common global trade finance platform with local regulatory and client requirements? What should be standardised, and where is flexibility essential?
A global platform should aim to standardise what creates scale while remaining flexible where local market requirements genuinely differ.
Core processes, data models, controls, security frameworks and technology foundations should be standardised as much as possible. This reduces complexity, improves resilience and accelerates innovation.
At the same time, trade finance is inherently international. Regulatory requirements, market practices and client expectations can vary significantly across jurisdictions. A successful global platform must therefore be designed to accommodate local variations through configuration and governance rather than through fragmented systems.
The challenge is finding the right balance between consistency and adaptability.
Digital Trade Outlook: Beyond AI and data interoperability, which technology priority will matter most to trade finance over the next three years, and what should banks do now to prepare?
Beyond AI, I believe the most important priority will be simplification.
Many trade finance institutions still operate highly complex, sometimes obsolete, technology landscapes that have evolved (or not) over decades. Complexity slows innovation, increases costs and makes change more difficult.
Over the next three years, the institutions that create the most value will be those that simplify their architecture, increase automation, strengthen their engineering capabilities and build platforms that are easier to evolve. This involves cloud migration and legacy modernisation to improve data accessibility and allow legacy systems to interact with fintechs and newer technology. It also involves API integration, which is becoming essential for large corporates willing to plug banking capabilities directly into their ERP systems. AI will certainly be transformative, but it will deliver the greatest impact when it is deployed on top of simpler, better integrated and more scalable foundations. In many ways, simplification is the enabler that makes every other innovation possible.
Read more conversations on trade finance technology and transaction banking in our Executive Voice series.
The conversation continues
Join the discussion on LinkedIn
Digital Trade Outlook shared this interview with Arnaud Declochez on LinkedIn. Read what peers are saying and add your view.
Join the discussion on LinkedIn ↗Join the discussion on X ↗